

Huntington Mobile Banking analysis by Appwee
Managing a bank account from a phone sounds simple until the moment you need to check a balance in a supermarket queue, confirm whether a payment has cleared, or move money while you are away from your desk. Huntington Mobile Banking is built for those small but important moments. I found it most useful as a practical connection to Huntington accounts rather than as a replacement for every banking conversation or financial tool.
Developed by Huntington National Bank, this free finance app is aimed at customers who want to handle everyday banking from a mobile device. Its broad appeal is reflected in an average rating of 4.8 from around 78 thousand ratings, with more than a million installs. That does not guarantee that every person will have the same experience, but it does suggest that the app has become a regular part of many customers’ routines.
The important thing to understand before installing it is that its usefulness depends heavily on the quality of the connection available when you need it. Banking information has to be current, and actions involving accounts need a reliable exchange with the bank’s systems. In my experience, that makes the app feel quick and convenient when the network is behaving, but less reassuring when a weak signal interrupts a task at the wrong time.
What daily banking feels like on a phone
Fast answers when the connection is good
The strongest part of Huntington Mobile Banking is the way it reduces small banking chores to brief phone sessions. Instead of waiting until I am at a computer, I can open the app during a spare minute and get a clearer picture of my accounts. That is especially useful before making a purchase, paying a bill, or deciding whether a transfer can wait.
This kind of convenience is easy to underestimate. A desktop banking website may offer a larger layout, but it also asks me to find a browser, remember where I saved the login page, and sit down long enough to use it comfortably. The mobile app fits better into the scattered rhythm of real life. I can check in while travelling, between errands, or just before leaving a restaurant.
Connectivity is part of that experience from the start. A strong Wi-Fi or mobile-data connection generally makes the app feel like a live window into the account. A poor connection changes the mood completely: screens may take longer to load, and I become more cautious about repeating an action because I do not want to create confusion about whether it went through.
A realistic grocery-store scenario
Imagine standing in a checkout line and wondering whether a recent deposit is reflected in the available balance. This is exactly the kind of situation where a banking app earns its place on a phone. I can check the account without opening a laptop, compare the balance with the purchase I am about to make, and continue with a more informed decision.
The same scenario also shows the app’s limitation. A crowded store can mean inconsistent reception, and a basement or large building may weaken the connection. If the balance screen is slow to refresh, I would not treat an old-looking screen as proof that nothing has changed. I would wait for the account information to load properly rather than making a second attempt at an action simply because the first screen did not respond immediately.
That habit is more important with banking than with ordinary shopping apps. A delayed social feed is harmless; uncertainty around a transfer or payment can create real stress. My practical advice is to use the app for quick checks in busy places, but reserve more complicated account work for a moment when the connection is stable and you have time to verify the result.
Useful in motion, less comfortable for deep review
The phone format is ideal for short sessions, but it is not automatically the best environment for studying every detail of personal finances. When I want to compare several transactions, think through a larger budget, or inspect a long period of activity, a computer’s wider screen is usually easier on my eyes and attention.
That is not a failure of Huntington Mobile Banking. It is a trade-off shared by most mobile banking tools. The app’s value is strongest when the question is direct: what is available, what has recently happened, or what do I need to handle now? For broader financial planning, I would pair it with a budgeting method rather than expecting the banking app alone to explain spending habits.
Who will get the most from it
I would recommend it first to Huntington customers who regularly manage money away from home. It makes sense for someone who checks balances before purchases, wants a convenient way to stay aware of account activity, or prefers handling routine banking through a phone instead of a browser.
It is also a good match for people who value immediate access more than elaborate financial analysis. The app can become a useful daily checkpoint: open it, confirm what matters, complete the necessary task, and close it. That workflow is less intimidating than waiting for a monthly statement to discover that a payment or purchase was easy to overlook.
I would be more cautious about recommending it to someone who does not bank with Huntington, since a mobile banking app is naturally tied to its own institution. I would also steer away from making it the sole tool for someone who needs detailed investment analysis, complex household budgeting, or a broad view of accounts held at several banks. A dedicated finance service or a full desktop setup may be better for those needs.
How it compares with the usual alternatives
Compared with using a mobile browser, a dedicated banking app usually feels more natural for repeated account checks. The phone app is already designed around a smaller screen and a touch-first routine, while a browser session can feel like a compressed version of a desktop site. For an occasional customer, the difference may not matter much. For someone checking in several times a week, the app is the more comfortable habit.
Compared with a budgeting app, Huntington Mobile Banking serves a different purpose. A budgeting tool may help organize spending across categories or institutions, while a bank app is closer to the source of account information. I prefer using the Huntington app when I need the bank’s current view and a separate budgeting method when I want to interpret the bigger picture.
Compared with visiting a branch or calling the bank, the app is faster for straightforward tasks that fit comfortably on a phone. It does not replace personal help when a situation is unusual, disputed, or difficult to explain through a screen. That distinction matters: convenience is not the same as complete support for every financial problem.
When the network becomes the main issue
There are three different connection situations worth separating. The first is a normal, stable session, where the app opens and account information appears without much friction. The second is a slow session, where waiting becomes part of the task. The third is an interrupted session, where I am no longer certain whether the app has received or completed an instruction.
The third situation deserves the most care. If an action appears to stall, I would not immediately tap the same control repeatedly. I would first give the screen time to settle, then look for a visible confirmation or updated account activity before trying again. If the result remains unclear, moving to a more reliable connection and checking again is safer than guessing.
This is one of the less obvious skills involved in mobile banking: knowing when not to interact. On a social app, repeated taps are merely annoying. In a financial app, they can create uncertainty about duplicate actions. Huntington Mobile Banking can make banking quicker, but it still requires the user to slow down when the network is unreliable.
Recovery after a failed or interrupted session
My preferred recovery routine is simple. I stop tapping, note what I was trying to do, and wait until I have a dependable connection. Then I reopen the relevant account view and check whether the information has changed before taking another step. This approach is particularly useful when I am away from home and the signal shifts between Wi-Fi and mobile data.
I also avoid treating a frozen screen as a final answer. A screen that has not refreshed is not necessarily a confirmation that nothing happened. The safer question is whether the account view or activity record now shows a clear result. That extra check takes a little longer, but it reduces the chance of acting on an assumption.
For sensitive tasks, I would choose a quiet setting rather than completing them while walking through a station or juggling shopping bags. A stable connection helps, but so does having enough attention to read each screen carefully. The app is designed for mobile use; that does not mean every mobile moment is equally suitable for banking.
If the app itself is not behaving as expected, the sensible next step is to try again later from a stronger connection and use Huntington’s normal support channels when the problem continues. I would not keep reinstalling or repeatedly submitting the same request without first checking the account status. Recovery is as much about avoiding an unnecessary second action as it is about getting the first screen to load.
Using it without wasting mobile data
Most people will not need to treat ordinary banking checks as a major data burden, but connectivity still affects how and when I use the app. If I am in an area with a weak signal, I prefer to postpone non-urgent account browsing until I have dependable Wi-Fi or better mobile service. That is less about saving data than avoiding a half-loaded session that leaves me unsure what is current.
A useful routine is to group several small checks into one deliberate session instead of opening the app repeatedly throughout the day. I might review the balance, inspect recent activity, and handle the one task that actually needs attention before closing it. This reduces interruptions and makes it easier to remember what I have already confirmed.
I would also avoid using public Wi-Fi casually for sensitive banking unless I trust the network and understand the risks. A private connection is a better choice for account work, especially when the task involves more than simply looking at a balance. The app’s convenience should not encourage careless habits around connectivity or phone security.
For travellers, the best approach is to plan ahead without assuming that every location will provide a dependable signal. I would check important account information before entering a poor-coverage area and avoid leaving urgent banking tasks until the last minute. The app is most helpful when it gives me flexibility, not when I expect it to overcome every network problem.
Security and everyday phone habits
Banking from a phone means the device itself becomes part of the security picture. I would keep the phone protected with its normal screen lock, avoid handing an unlocked device to someone else, and be careful when opening the app in crowded public places. These habits are not flashy features, but they have a direct effect on how comfortable mobile banking feels.
I would also pay attention to where I am when checking financial information. A quick glance in a private corner is different from displaying account details in a packed bus. The app makes access easier, which is useful, but easier access also means I need to be more deliberate about who can see the screen.
The Everyone content rating makes the app broadly suitable from an age-classification perspective, but that should not be confused with giving a child unsupervised access to a bank account. Financial responsibility and phone access are separate questions. I would treat the app as a personal banking tool and set up access accordingly.
Version, access, and practical setup
The current version is 6.78.204, and the app requires at least OS 10. Before installing, I would check that the phone meets that requirement and has enough room for normal app updates. This is a small step, but it prevents the frustrating situation of expecting a banking app to work on an older device that cannot support it properly.
Because Huntington Mobile Banking is free, the decision is less about purchase cost and more about whether it fits the way you bank. The real prerequisites are being a Huntington customer, having a compatible phone, and being comfortable using a connected mobile session for account access. Someone who prefers branch visits or paper records may not gain much from installing it.
I also recommend treating updates as part of normal maintenance rather than postponing them indefinitely. Banking software needs to remain compatible with the phone and the bank’s systems. Updating does not make a weak signal stronger, but it can prevent avoidable problems caused by running an outdated app.
Small routines that make the app more dependable
My most useful routine is to separate checking from acting. First I look at the account and recent activity; then, only after the information has loaded clearly, I decide what to do. That pause is especially valuable when I am on mobile data or moving between networks.
Another practical habit is to use a stable connection for anything that would be difficult to untangle later. A quick balance check can wait through a short delay, but an important payment or transfer deserves a calm setting, a readable screen, and enough time to verify the outcome. This is a simple trade-off between speed and confidence.
I would also keep the app’s role clear in my overall money routine. It is excellent for staying close to Huntington accounts, but it is not a substitute for a spending plan, emergency-fund strategy, or careful review of recurring expenses. The app gives me access; I still have to make the financial decisions.
My connectivity verdict
After using Huntington Mobile Banking as an everyday account companion, I see its main strength as dependable convenience when the connection is solid. It brings routine banking into the moments when people actually need answers: before a purchase, during a busy day, or while away from a computer. That immediacy is the reason I would choose it over repeatedly signing into a browser.
Its main limitation is also clear. A mobile banking session is only as reassuring as the connection and attention behind it. Slow loading, changing reception, or an interrupted action can turn a quick task into a question about what really happened. The app cannot remove that uncertainty, so the user needs a careful recovery habit instead of repeated taps.
With more than a million installs and a strong 4.8 average, it is easy to see why this free finance app has become a familiar choice for Huntington customers. I would recommend it to anyone who wants convenient access to everyday banking and is willing to use it thoughtfully. I would skip it as a primary financial tool if I needed cross-bank budgeting, detailed analysis, or a fully offline workflow.
My final recommendation is straightforward: install it if your banking relationship is with Huntington and you want your accounts close at hand. Use a reliable connection for important actions, verify results after delays, and remember that the app is a practical window into your bank rather than a complete financial planning system. Used with those expectations, Huntington Mobile Banking is a focused and useful companion for connected, day-to-day banking.
Gallery
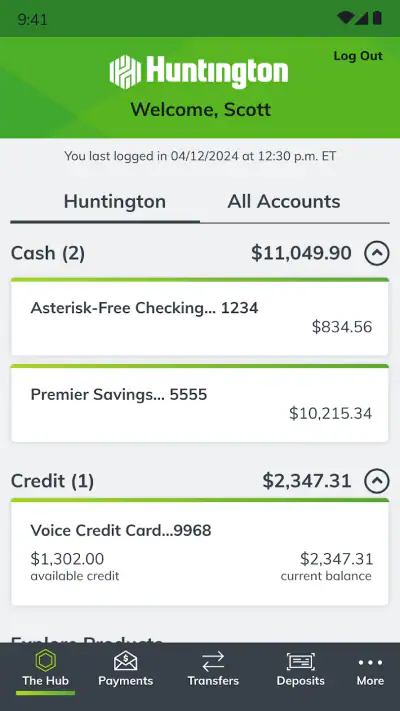
Huntington Mobile Banking Pros and Cons
- Quick access to balances
- transactions
- and account details
- Mobile check deposit saves a trip to a branch
- Bill pay and transfers are convenient from one app
- Card controls help manage security and spending
- Biometric login makes sign-in faster and easier
- Some features may require enrollment through online banking first
- Mobile check deposits can take time to become available
- App performance may vary during maintenance or peak periods
- Not all banking services can be completed in the app
- Availability of features may depend on your account type
Huntington Mobile Banking Frequently Asked Questions
What is Huntington Mobile Banking, and what can I do with it?
Huntington Mobile Banking is the official mobile app for Huntington customers, providing access to everyday banking services from an Android or iOS device. After signing in, you can review account balances and transactions, transfer money between eligible accounts, deposit checks, pay bills, manage debit cards, locate branches or ATMs, and receive account alerts. Available features may vary depending on your account type and location.
Is Huntington Mobile Banking safe to use?
The app is designed with standard banking security measures, including secure sign-in, encryption, device authentication options, and fraud monitoring features. You should still protect your phone, use a strong and unique password, avoid logging in over unsecured public Wi-Fi, and keep the app and operating system updated. Huntington will not ask you to share sensitive credentials through suspicious messages or unofficial links.
Can I deposit checks with the Huntington Mobile Banking app?
Eligible customers can generally use the app’s mobile check deposit feature by photographing the front and back of an endorsed check and submitting it for review. The images must be clear, the check must meet Huntington’s requirements, and deposit limits or availability times may apply. Keep the original check safely until the deposit is confirmed, then destroy it according to the bank’s instructions.
Does Huntington Mobile Banking support bill payments and money transfers?
Yes, the app can provide convenient tools for paying eligible bills and moving money between supported Huntington accounts. Depending on your setup, you may also be able to send money through available person-to-person payment services or transfer funds to external accounts. Processing times, daily limits, fees, recipient enrollment, and eligibility can differ, so review the details carefully before confirming a transaction.
What should I do if I cannot log in or notice suspicious activity?
If you cannot access your account, first check your internet connection, update the app, and use the official password or username recovery options rather than third-party websites. If your phone is lost, your credentials may be exposed, or you see an unfamiliar transaction, contact Huntington through the official app, website, or phone number shown on your card or statement. Never share verification codes with anyone.














